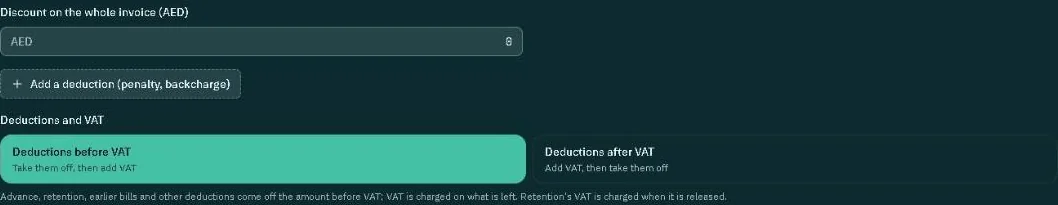
Most contractors have had a claim come back lighter than it went out. A delay penalty. A backcharge for cleaning, or for a damaged door the main contractor says was yours. Some of these you argue, and some you accept because the job matters more than the argument.
Once a penalty is accepted, the VAT question is simpler than it looks, as long as you keep it apart from retention. Both sit in the deductions block of a claim, but for VAT they work in opposite ways.
A penalty is not retention
Retention is your money, held back and paid later. A penalty is money you will never receive, and the VAT follows from that difference.
A penalty, a delay charge or a backcharge reduces the value of the contract. So it reduces the taxable value under both methods, and it carries no VAT at any later point. There is nothing to release and nothing left to declare.
| Deduction | What it is | Its VAT |
|---|---|---|
| Retention | Part of the price, paid later | Declared once: at the release before VAT, on the claims after VAT |
| Advance recovery | Money already received | Declared once, on the advance tax invoice |
| Penalty or backcharge | A cut in the contract value | Never charged: it comes out of the taxable value |
Put another way: retention and the advance are timing. The money moves earlier or later, and its VAT is declared once, at one end or the other. A penalty is not timing. The money never moves at all, so there is no VAT to place anywhere.
The 945,000 example, both ways
Take a contract of 1,000,000 with a 10% penalty of 100,000. The supply is now worth 900,000, and its VAT is 45,000. Both methods arrive there.
- Contract1,000,000.00
- −Penalty 10%100,000.00
- =Taxable amount900,000.00
- +VAT 5%45,000.00
- =Total945,000.00
- Contract1,000,000.00
- +VAT 5%50,000.00
- =Including VAT1,050,000.00
- −Penalty with its VAT105,000.00
- =Total945,000.00
VAT payable on this invoice: 50,000.00 − 5,000.00 = 45,000.00
| Line | Before VAT | After VAT |
|---|---|---|
| Contract | 1,000,000.00 | 1,000,000.00 |
| VAT on the contract | — | 50,000.00 |
| Less penalty | −100,000.00 | −105,000.00 |
| VAT on the net | 45,000.00 | — |
| Total | 945,000.00 | 945,000.00 |
After VAT, the 105,000 is the penalty with its VAT. The invoice still shows 50,000 of VAT on its first VAT line, because that is 5% of the work. But the VAT payable on the invoice is 45,000, not 50,000. The 5,000 inside the penalty is not charged, because the client is not paying it.
If you treat the penalty like retention and leave it in the VAT base, you declare 50,000 and collect VAT on only 900,000. The 5,000 difference comes out of your pocket.
How it prints, and the row that makes it add up
On a tax invoice the deductions print in the order the VAT was worked out, and the VAT line is always 5% of the figure directly above it. Before VAT that is plain:
| Line | Amount |
|---|---|
| Total before VAT | 1,000,000.00 |
| Less: Penalty | −100,000.00 |
| Taxable amount | 900,000.00 |
| VAT (5%) | 45,000.00 |
| Total | 945,000.00 |
After VAT, the tax block needs one more row. Without it, the VAT line says 50,000, the return says 45,000, and nobody reading the invoice can see why.
| Line | Amount |
|---|---|
| Total before VAT | 1,000,000.00 |
| VAT (5%) on 1,000,000.00 | 50,000.00 |
| Less: VAT on penalty | −5,000.00 |
| VAT payable on this invoice | 45,000.00 |
| Total including VAT | 1,050,000.00 |
| Less: Penalty | −105,000.00 |
| Total | 945,000.00 |
Check it the same way as any after-VAT invoice. The tax block: 50,000 − 5,000 = 45,000. The money: 1,000,000 + 50,000 − 105,000 = 945,000.
A penalty on a claim with an advance and retention
Real claims carry more than one deduction. Here is claim 1 of the reference contract (300,000 of work, a 30% advance, 10% retention) with a 5% delay penalty on top.
| Line | Before VAT | After VAT |
|---|---|---|
| Work certified | 300,000.00 | 300,000.00 |
| VAT on the work | — | 15,000.00 |
| Less advance (30%) | −90,000.00 | −94,500.00 |
| Less retention (10%) | −30,000.00 | −31,500.00 |
| Less delay penalty (5%) | −15,000.00 | −15,750.00 |
| VAT on the net | 8,250.00 | — |
| Payable | 173,250.00 | 173,250.00 |
After VAT the claim declares 15,000 − 4,500 − 750 = 9,750: the VAT on the work, less the VAT already declared on the advance, less the VAT inside the penalty. Before VAT it declares 8,250, and the gap of 1,500 is the retention's VAT, which waits for the release.
In this example the retention is 10% of the work certified, not of the work less the penalty. Mizarah works it the same way. Follow what your own contract says.
Before you accept one, pin down four things
Arguments about penalties are often less about whether the penalty is fair than about what exactly it is. A note on a certificate that says "less delay penalty" leaves too much open. Before it goes on your claim, get these answered in writing:
- The amount, or the percentage and what it is a percentage of: the whole contract, this claim, or the work left.
- Whether a fixed figure includes VAT or not.
- Which claim it comes off, so it is taken once and not again on the next certificate.
- Whether it is final, or still under discussion. Only an agreed penalty belongs on a tax invoice.
The third point catches more people than you would think. A penalty that sits on the main contractor's running certificate can appear on every certificate after it, as part of the cumulative figures. Take it once, on the claim it belongs to, and check that your next claim does not take it again.
A fixed backcharge: which number did you type?
Backcharges often arrive as a round figure: 10,500 for cleaning, say. Before VAT, a fixed amount is an amount before VAT. After VAT it includes VAT. The same typed number is a different deduction under each method.
| Line | Before VAT | After VAT |
|---|---|---|
| Work certified | 300,000.00 | 300,000.00 |
| VAT on the work | — | 15,000.00 |
| Less backcharge | −10,500.00 | −10,500.00 |
| Taxable value | 289,500.00 | 290,000.00 |
| VAT declared | 14,475.00 | 14,500.00 |
| Payable | 303,975.00 | 304,500.00 |
After VAT the 10,500 is read as 10,000 plus 500 of VAT, so the claim declares 15,000 − 500 = 14,500.
So before you type a backcharge into a claim, find out whether the main contractor's figure includes VAT. If theirs does and your method reads it as a figure before VAT, the two of you will be 525 apart on this one claim, and the conversation about why will take longer than the claim did.